ES
 IT
 PT
 DE
 NL


Greg, you’ve raised the issue of media rights as a major factor in the pressure faced by retail betting shops. How significant have increases in racing media rights become?
The increases have been substantial. Five years ago, our media rights costs were approximately £40,000 per shop per year including VAT. Three years ago, that had risen to around £50,000. This year, we’re looking at a staggering £70,000 per shop.
Every betting shop is different and independents operate on a different payment mechanism to the majors, so you have to be careful about generalising across the industry. But for us, that represents an increase of around 75 per cent in five years, and I think you would find a similar story elsewhere.
The bigger concern is that I don’t believe there is a true understanding among the media rights companies of the cost pressures facing retail betting. At times, it feels as though they think we’re bluffing.
I was effectively told by one media rights company: “If it’s that bad, why don’t you shut more shops? Independents haven’t shut enough shops for us to believe you can’t pay more.” In other words, because you’re still operating, there must be scope to charge you more. That is clearly not a sustainable way of looking at the market.
Why have media rights received less attention than tax and employment costs?
I understand why larger operators want to highlight taxation. They also operate significant online businesses and naturally want government to consider the impact when future tax decisions are made. I no longer run an online business, so I’m not suggesting their position is wrong. But when we’re specifically discussing retail, I struggle with the argument that online taxation is responsible for closing betting shops.
If I have a marginal shop making money, I’m going to keep it open because it is still profitable. Generally, the shops being closed are those that were already losing money.
What I do know is that the combined increases in racing media rights coming into effect in 2026 were higher for us than the additional costs of National Insurance and the minimum wage combined. When our own media rights bill has gone from around £40,000 per shop five years ago to £70,000 today, that puts the scale of the issue into perspective.
How much negotiating power do independent bookmakers have?
Very little. It is like telling a pub that it has a choice between selling beer and not selling beer. Technically there is a choice, but commercially there really isn’t. These are whole-estate contracts, so we can’t cherry-pick. We can’t decide that one shop takes plenty of racing and therefore needs the service, while another is predominantly football or machines and doesn’t. Consequently, we have individual shops where the revenue generated by racing comes nowhere near covering its cost.
Around half of our estate is in London boroughs, where competition can be extremely close. I can’t operate a shop 100 yards from a competitor and simply not show racing when they do. In practical terms, it becomes a take-it-or-leave-it proposition.
Betfred took a stand against this earlier this year – effectively going dark. Did it change anything?
I thought it was a brave decision because you’re exposing yourself to customers voting with their feet and going to a competitor. You are effectively taking a stand that could benefit the businesses you compete against. Betfred must have felt extremely strongly about the issue to take that step. We didn’t feel able to make the same stand because we simply don’t have its scale or high-street presence. Had the situation continued for longer, it would have been interesting to see what happened because the rights holders would have been losing significant revenue. When the next round of negotiations comes around, I believe you will see a much more united position from bookmakers. There is considerable frustration across the industry.
Is racing still economically viable for betting shops?
There are certainly individual locations where racing revenue comes nowhere near covering the associated costs. Across the company as a whole, once everything is taken into account, the margin is now very limited. At the same time, racing remains important because it brings customers through the door. I certainly wouldn’t want to operate without it.
The difficulty is that we also hear racing argue that it doesn’t receive enough money through the Levy, while maintaining that Levy payments and media rights should be viewed separately. From a retail bookmaker’s perspective, they are both costs associated with funding racing, so inevitably we look at the overall amount being paid.
Is the current media rights model sustainable?
Not indefinitely. There is a danger of creating a destructive cycle. Betting shops close, racing loses income from those shops and the temptation is then to recover that revenue by charging the remaining estate more. That makes additional shops uneconomic and potentially accelerates further closures.
Most operators have now signed two or three-year media rights contracts, so in the immediate term we are where we are. But if rights holders try to extract substantially more from the remaining estate over the next three to five years, the outlook becomes very difficult. At some point racing could find itself asking how the retail footprint became so small. If that happens, the cost of media rights will have played a significant part.
Does British racing need to rethink its relationship with retail betting?
Yes, although I can only speak confidently about retail because I don’t know enough about the structure of online revenues. One of racing’s broader challenges may be that we simply have too many racecourses and too much content.
Bookmakers might have to accept receiving less content, but racing may also have to accept that some rationalisation is necessary if we are going to have a product that bookmakers can continue to buy at an affordable price. Otherwise, there is a risk that the current model ultimately cannibalises itself.
Why has Jenningsbet been able to expand while others are closing shops?
We have the advantage of being a long-established business. My grandfather started the company and Jennings is actually my mother’s maiden name. We have mature shops that have traded since the 1960s in locations that have historically performed well. Although we’ve grown beyond 200 shops, we spent around 15 years at roughly 100, so this hasn’t been a sudden expansion. Much of our growth over the last five years has come through acquiring other independents.
I also think we have developed a strong formula. We’ve built a recognisable brand among retail betting customers, including through sponsoring seven or eight greyhound stadia, and we invest around £200,000 on average in every branch we acquire or open organically. That level of investment is important.
Then it comes down to people. We want good employees and we invest in training them properly. Ultimately, the formula is relatively straightforward: the right location, appropriate investment and good people. However, it doesn’t mean every shop succeeds. I closed a branch recently because we simply couldn’t make the economics work, with a rent review proving the final factor. We’re not immune to the pressures facing the sector, but the model continues to work for us.
Is the decline in shop numbers really a process of ‘right-sizing’?
I believe so. Fewer people bet in shops because a significant proportion of customers have migrated online, so logically there need to be fewer betting shops. There was an old rule of thumb in retail development that there should be roughly one betting shop for every 7,000 people. Today, I think the figure is closer to one for every 12,000.
But the Gambling Commission figures illustrate an important point. In 2018/19, retail betting GGY was around £3.1bn across 8,320 betting shops. By 2024/25, GGY had fallen to £2.5bn and the estate to 5,825 shops. So while overall GGY has declined by almost 20 per cent, average GGY per shop has actually increased from around £370,000 to £429,000 – a rise of approximately 16 per cent.
That tells you something important about what is happening in retail.
The overall market has contracted, but the shops that remain are, on average, generating more revenue. I now operate as the sole bookmaker in some locations with populations of around 12,000 and those can be extremely good shops.
That’s what I mean by right-sizing. There may be fewer people betting in retail, but the shops that remain in the right locations can generate more revenue because the market is no longer oversupplied. If a town can support four betting shops, four can work successfully. Put six into the same market and you risk making all six uneconomic.
The government is looking to remove the ‘aim to permit’ principle for betting shops. What will this mean for the industry?
It looks as though we could be heading back towards the environment we had before the Gambling Act 2005. In the 1990s and early 2000s, if you wanted to open a betting shop, you went to the magistrates’ court and had to demonstrate that existing demand wasn’t already being met. At times, that could make opening a new shop extremely difficult.
Removing “aim to permit” potentially takes us back in that direction by giving local authorities much greater discretion over whether a new gambling premises licence should be granted. For betting shops specifically, I struggle to see the problem this is intended to solve. Organic expansion is already tiny.
I think I opened more new shops than almost anyone last year, apart perhaps from BoyleSports, and the grand total was four net new shops. We are talking about an industry whose physical footprint has already contracted enormously.
I suspect much of the political concern is driven by adult gaming centres, but betting shops are being caught up in the same conversation. There are significant differences between the two. Betting shops contribute to British horseracing, employ more people and provide somewhere for customers to watch live sport and socialise. Yet politically, different types of gambling premises are often treated as though they are interchangeable.
Are local gambling impact assessments another concern?
Yes, because the question is how objective those assessments will ultimately be. I can understand the frustration of a local authority that sees several gambling premises clustered together on the same high street. Betting shops used to cluster too, but we largely don’t anymore because the customer demand simply isn’t there to support it.
The danger is that councils look at betting shops, adult gaming centres and other gambling premises collectively rather than considering the very different businesses operating behind those licences. If an impact assessment starts from the premise that another gambling venue is inherently undesirable, it creates another barrier to opening a betting shop regardless of the individual circumstances of that location.
There is another side to this too. If opening new shops becomes significantly harder, existing licensed estates potentially become more valuable. Anyone wanting to enter or expand within the retail betting market may increasingly have to acquire an existing operator rather than grow organically. So, the changes could restrict future expansion while simultaneously increasing the strategic value of the shops and licences already in the market.
Are betting shops being unfairly blamed for the high street decline?
I think they are being used as a convenient part of a much broader narrative. We’re opening a shop in Hemel Hempstead in a unit that had been empty for two years. There wasn’t a butcher, baker or independent retailer waiting to take it. It was simply vacant.
For decades, high-street retailers have warned successive governments about the impact of the business rates system and competition from online retail. Alongside that, you have the growth of out-of-town retail, parking costs and underinvestment in town centres.
Those factors have contributed to empty units and declining high streets. It seems unreasonable to create an environment in which premises remain vacant and then blame the businesses prepared to invest in filling them. Betting shops did not create the structural problems facing the British high street.
What does the retail betting sector look like five years from now?
If you leave it purely to economic forces, I don’t believe this is an industry in terminal decline. We face significant cost pressures, as every business does, and we have to manage them. Racing costs are probably my biggest economic concern, but customers are still coming through the doors and revenues are holding up, if not improving. The fact that average GGY per shop has risen by around 16 per cent since 2018/19 reinforces that point. From a purely commercial perspective, I wouldn’t describe the outlook as spectacular, but I would certainly be reasonably positive.
The greater concern is political because that is something individual operators have very little control over. You can invest in your estate, find the right locations and employ and train the right people, but those efforts can be undermined very quickly by policy decisions.
At the same time, the industry has to recognise why gambling generates strong opinions. There are people whose lives have been harmed by gambling. There needs to be balance, effective regulation and appropriate safeguards.
We also need to recognise that the industry can operate within an echo chamber. On platforms such as LinkedIn, we often speak to people who broadly agree with us, while those with completely different views may never hear our argument. Bridging that gap is important. The retail betting industry has a case to make, but we need to make sure we are communicating it beyond our own audience.
Racing Risks Pricing out the Bookies
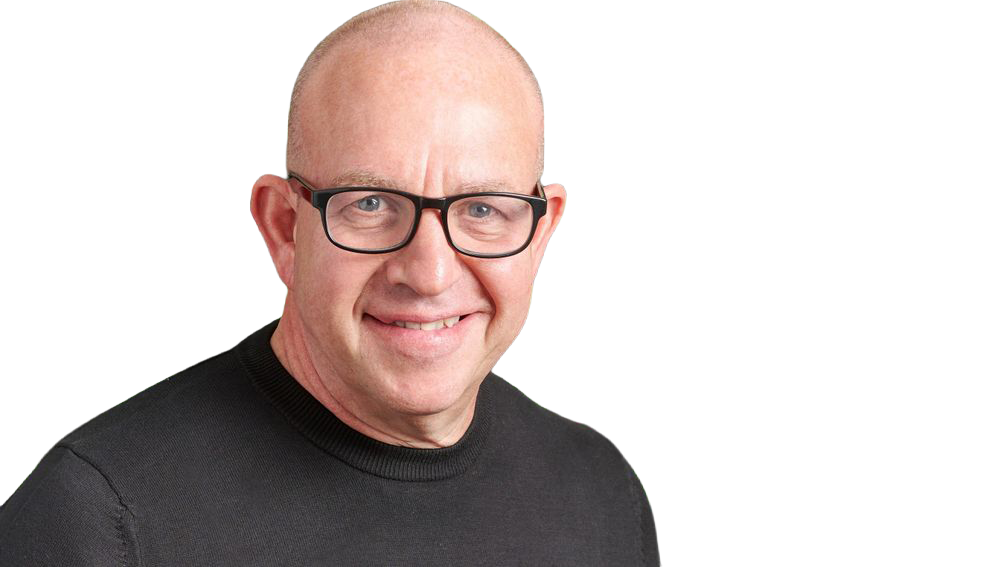
Jenningsbet CEO Greg Knight believes the debate around Britain’s shrinking betting shop estate is overlooking one of its biggest pressures: the escalating cost of racing media rights. Speaking to G3, Knight explains why the current model risks becoming unsustainable, how Jenningsbet has doubled its estate while larger rivals retrench, and why political intervention now worries him more than the underlying economics of retail betting.