ES
 IT
 PT
 DE
 NL


European lotteries are not short of scale. The sector generates around €109bn in annual sales and €46bn in GGR, while returning almost €30bn to society. Yet beneath those numbers sits a contradiction: lottery remains an overwhelmingly retail business at a time when the wider gambling and entertainment markets are increasingly digital.
During EveryMatrix’s media event in Copenhagen, Head of Lottery Nikolina Gabelica highlighted that just 13.4 per cent of European lottery GGR currently comes online. For traditional draw-based games, the figure is lower still at 7.6 per cent. The disparity between individual markets is equally significant. Norway has become Europe’s digital outlier, with eight in every €10 of lottery sales made online, while in Spain the equivalent figure is around €3 in every €100.
For Gabelica, however, the gap cannot simply be explained by some lotteries understanding digital better than others. “It also depends on the country where you are living,” she tells G3. “Do you have internet penetration and mobile penetration on the same level as another country? Nordics are also advanced in digital payments.”
Local habits matter too. In parts of the Balkans, she notes, cash remains important to players, as does the anonymity afforded by retail betting and lottery purchases. “I don’t think it’s about them not having the ability or the technology to have more games online. It’s the mentality as well.” What will eventually change that equation is the player.
Younger consumers already conduct much of their lives through their phones and Gabelica sees little reason to expect them to adopt traditional lottery purchasing habits simply because they reach legal playing age. “The switch will come because the players are changing,” she says. “They’re doing everything on their mobile. Once they grow old enough to play lottery or sports betting, they won’t be going to the shops. It’s convenient for them to do everything in life.” It’s a transition that has taken longer than Gabelica expected, but it is already exposing different levels of digital maturity across Europe.
Competition changes the lottery
Competition is one of the forces accelerating the process. The opening of gambling markets creates obvious commercial pressure, but Gabelica argues that lotteries are competing for attention beyond the regulated gambling sector. She points to games such as Candy Crush Saga as an example of the type of experience that has shaped younger consumers’ expectations around gamification and digital engagement.
“It’s not gambling, but it’s your competition,” she says. “I’m not saying the lottery should be fully like that, but some of the things younger players are used to have to be part of your product as well.”
Lotteries retain powerful brands, considerable revenues and, in many cases, exclusive access to traditional lottery products. Such advantages can also reduce the urgency to change. Retail also carries political and social significance. European lotteries support around 55,000 full-time jobs and operate through hundreds of thousands of points of sale. Moving customers online therefore has implications beyond a simple channel migration.
Norway could provide an important test of where that journey eventually leads. Norsk Tipping will withdraw its traditional retail gaming terminals at the end of 2027, moving game entry entirely to digital channels from January 2028, although Flax scratchcards will remain available through physical retail. “Digital grew so much that there is no need for retail points of sale,” explains Gabelica.
So, does that make a largely digital model the eventual endgame elsewhere? “To one extent, yes,” she says, although she does not expect retail to disappear across Europe. “People will still like to socialise in person. You need this human touch.” The distinction, she argues, is whether the transition is imposed or develops through player behaviour. In Norway, “it was not forced. It just came naturally.”
Digitising isn’t digital transformation
There’s another important distinction between putting lottery products online and building products specifically for digital players. Gabelica has seen lotteries take physical scratchcards and recreate them – almost literally – on a computer screen, with players using a mouse to mimic scratching the physical card. It may be a first step, but it demonstrates the distance between transferring an existing product to another channel and reconsidering the experience around the possibilities of that channel.
Despite expanding into eInstants, sports betting and, where regulation allows, casino-style content, Gabelica says lotteries generally continue to think of themselves first and foremost as lottery operators. Some have responded by developing separate digital identities. Austria provides one of the strongest examples through win2day, which sits alongside the Austrian Lotteries brand, but has developed substantial recognition in its own right.
“Everybody connects those two,” says Gabelica. “People in the market do not see them as two separate entities. They know win2day is online and this is Austrian Lotteries.” Elsewhere, a second brand can help separate different product verticals or address different types of player. In some jurisdictions, the separation is regulatory rather than purely commercial.
Whatever the branding strategy, trust remains one of the lottery sector’s most valuable assets. Players know the organisation behind the product and expect that winnings will be paid. But Gabelica cautions that creating a separate digital brand without maintaining a visible connection to that established identity risks surrendering some of that advantage.
The loyalty gap
Where lotteries have more catching up to do is in what happens after a player arrives. Across Europe there are around 90 million registered online lottery customers, yet Gabelica says only 22 per cent of lotteries have loyalty programmes. For an iGaming operator, where customer data, segmentation, retention and personalised offers sit at the centre of the commercial model, that’s a significant gap.
The problem can extend deeper into the technology stack. Some lotteries still struggle to bring information from different sales channels into a single place, making even reporting more difficult than it needs to be. This is why Gabelica identifies player account management and the underlying platform, rather than an individual game category, as one of the biggest technology opportunities for lotteries.
“The platform is the most significant piece of technology lotteries currently need,” she explains. “The wallets, the payments and so on – this is the main place to keep all the information from the players that you have. It’s the connector to integrating any of the systems.”
The issue is not that lotteries are unaware of these shortcomings, but solving them takes place in a very different environment from that of a private online operator. Lottery procurement is lengthy, legacy systems remain widespread and organisational structures can slow decision-making. There is also a cultural element. “It’s cultural, people, procurement, and then, yes, after all this you have the technology,” says Gabelica.
A private operator can integrate a supplier, game or payment method relatively quickly. For a lottery, the same change can take considerably longer. The mindset is changing, however. Gabelica increasingly sees lottery becoming part of the broader iGaming conversation rather than existing as an entirely separate industry.
“People are starting to realise this is only one industry,” she says. “They’re not two separate industries. It’s one, just with different verticals and different types of operators.”
No need for the ‘Big Bang’
Convergence also sits behind EveryMatrix’s decision to establish lottery as a dedicated business unit after more than a decade of supplying technology to lottery organisations. The company is now developing lottery-specific products including draw games, pool betting and eInstants, alongside the platform, payments, player management and other technology already developed across the wider EveryMatrix business.
For Gabelica, bringing technology from iGaming into lottery does not mean telling established operators to discard everything they already have. “They don’t need to do the Big Bang if they don’t want to,” she says. Instead, a modular approach allows individual components to be replaced over time, modernising around existing infrastructure before progressively removing legacy technology. “You can replace each component,” she explains. “You can swap them out on the go, and it can take you years to get the lottery up to date.”
The alternative is potentially self-defeating. A lottery could spend years procuring and implementing an entirely new system, only to discover that technology has moved again by the time it launches. “If you wait to change everything and do the Big Bang, how long will it take you to do it? Two years will pass and then you would again be behind with the technology,” she explains.
The challenge for suppliers is that lottery moves at its own pace. Selling into the sector is less transactional than conventional B2B iGaming and depends heavily on long-term relationships and trust. “You don’t go to a lottery to sell something,” says Gabelica. “It’s a matter of relationship building and trust. It’s therefore a much longer period than when you engage with a private operator.”
For all the talk of transformation, Gabelica is equally reluctant to portray retail as an obsolete model waiting to disappear. In many markets it remains enormously successful, while elsewhere regulation does not yet permit lotteries to make a substantial digital move. The future is, therefore, unlikely to be a simple migration from shops to smartphones. Instead, Europe appears set for an increasingly fragmented lottery landscape in which markets move at very different speeds.
What changes is the competitive benchmark. As lottery customers become accustomed to the convenience, personalisation and user experience available elsewhere in their digital lives, putting the existing product online won’t meet those expectations. It’s not so much about whether digital will grow, but what lotteries choose to do with it.
Lottery’s Digital Divide
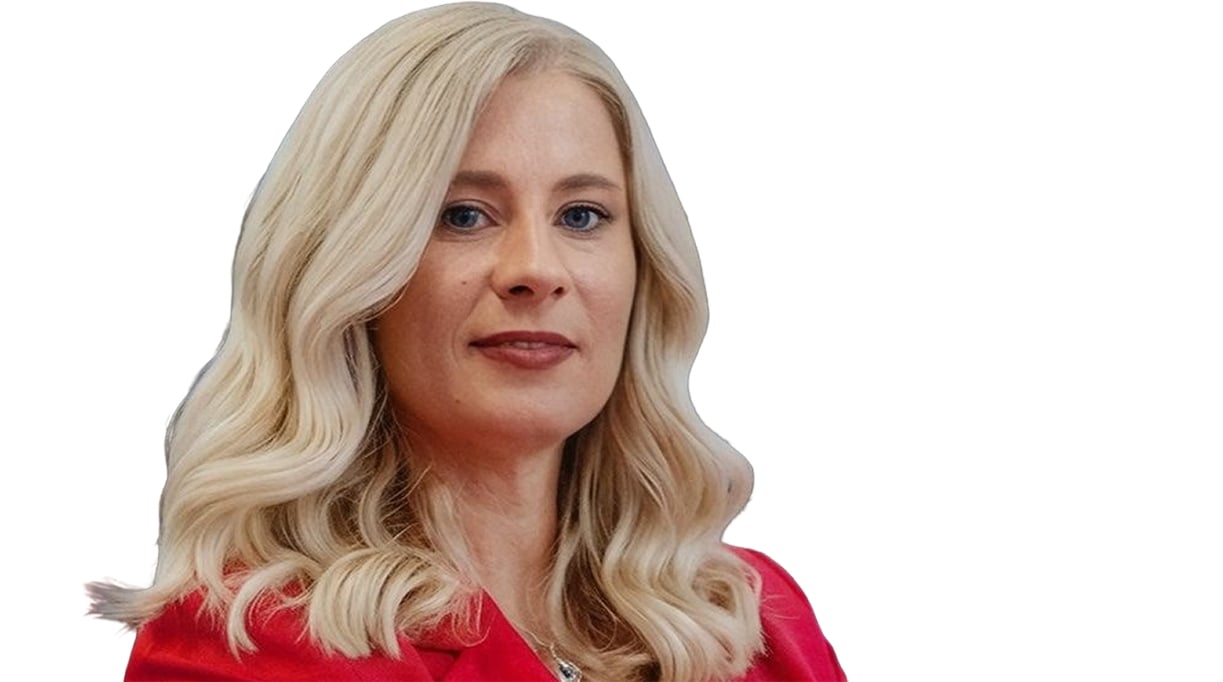
Nikolina Gabelica, Managing Director, Lottery at EveryMatrix, believes Europe’s lotteries have enormous advantages as they move online, but digital success requires more than transferring familiar retail products onto a screen. Speaking exclusively to G3 in Copenhagen, she explains why player behaviour, loyalty, technology and the changing role of retail are forcing lotteries to rethink how they compete.